



Outsourced credit control means paying a specialist provider to chase your invoices, handle payment queries and escalate overdue accounts on your behalf, instead of employing someone to do it. It suits businesses that have outgrown "the finance manager does it on Friday afternoons" but are not ready to hire a full-time credit controller, and businesses that have a credit controller but cannot cover holidays, sickness or growth. Whether it is worth the money depends on three numbers: what the provider charges, what a person would cost you, and how much cash is sitting overdue while nobody chases it. This guide puts real figures on all three, checked on 4 September 2026.
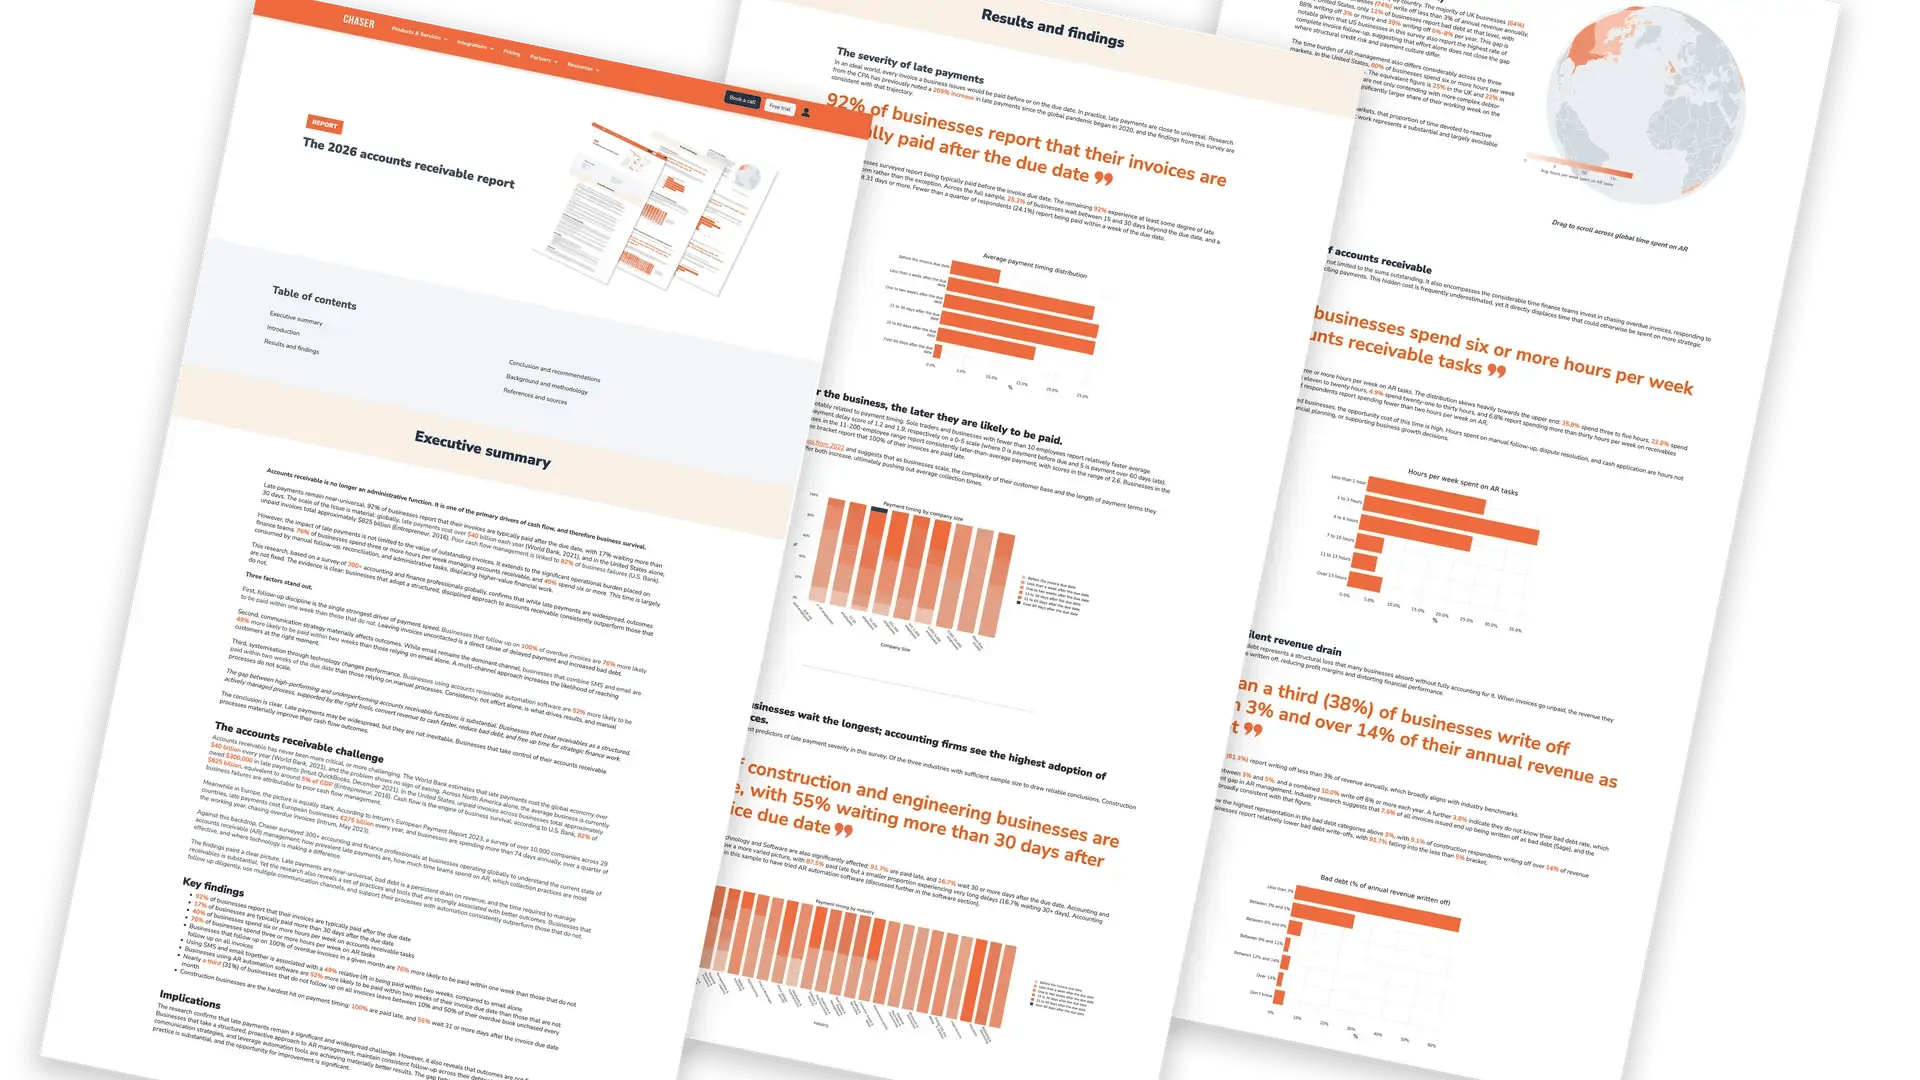
The context is not encouraging. According to Chaser's 2026 accounts receivable report, 92% of businesses say their invoices are typically paid after the due date, 17% typically wait more than 30 days, and 40% of finance teams spend six or more hours a week on receivables. That is the workload you are deciding what to do with.
What an outsourced credit control service includes
Providers vary, but a proper service covers the whole chasing cycle rather than just sending reminders. Checking the service pages of the providers ranking on page one for this search in the UK, and Chaser's own Chaser Care service, the common scope is:
- Reminder sequences before and after the due date, by email and usually by phone, in your company's name and tone.
- Query and dispute handling for the first line of "we never received the invoice" and "the PO number is wrong", with escalation back to you only when a decision is needed.
- Payment allocation and reconciliation, so a paid invoice is never chased and the ledger stays current.
- Reporting: aged debt, promises to pay, disputes, and what was said to whom.
- Escalation to formal collections or legal action, either through the same provider or a partner.
What is usually not included: raising invoices, setting credit terms, credit checking new customers (sometimes available as an extra), and anything that touches your accounting system directly. If a provider offers to "manage your receivables", ask which of the five items above are in scope and which are extras.
What outsourced credit control costs in the UK
Here is the honest position: of the outsourced credit control providers ranking on page one of Google UK for this search on 4 September 2026, none publishes a price. Every one of them quotes after a call. Looking further down the results, a small number of providers do publish a starting figure: Credit Control Assist advertises support "from £299 per month" and CM Group states "prices start from £597 + VAT per month" (both checked on their own websites, 4 September 2026). Treat those as the floor for a modest ledger, not a typical cost. Any article that gives you a confident "average price" without naming the provider is guessing.
What you can know in advance is the pricing model you will be offered, because there are only four:
| Model | How it works | What to watch |
|---|---|---|
| Monthly retainer | A fixed fee for an agreed number of hours, accounts or invoices per month. | The most predictable. Check what happens when your ledger grows past the band, and whether unused hours roll over. |
| Hourly or day rate | You pay for time spent, often with a minimum commitment. | Cheap when the ledger is clean, expensive when it is not. Ask for time reports. |
| Percentage of cash collected | The provider takes a share of what they bring in, common at the collections end. | Aligns incentives, but rewards chasing the easy money. Check whether routine on-time payments count as "collected". |
| Software plan plus a named specialist | A credit control platform with a dedicated person operating it for you, priced as an add-on to the software. | You keep full visibility of the platform. Confirm how much of the specialist's time you get and who covers their absence. |
The quote you get will move on four things: how many customer accounts and invoices you have, how many channels you want used (email only, or phone and letters too), how much dispute handling you expect, and whether you want collections escalation included or priced separately. Go into the call with those four numbers and the quotes become comparable.
What a credit controller actually costs to employ
This is the comparison that matters, and it is usually done badly because people compare a provider's fee with a salary rather than with the full cost of employment.
The salary. On 4 September 2026, Indeed UK put the average credit controller salary at £28,513 a year, and Totaljobs put the industry average at £32,400 with a typical range of £26,500 to £40,700. Senior and London roles sit at the top of that range or above it.
The on-costs. For the 2026 to 2027 tax year, employer National Insurance is 15% on earnings above £5,000, and the minimum employer pension contribution under auto-enrolment is 3% of qualifying earnings (both from gov.uk). On a £30,000 salary that adds roughly £3,750 in National Insurance and £700 to £800 in pension, before you count recruitment fees, training, equipment, a software licence and cover when they are away.
Illustrative in-house cost, 2026
Average salary £28,500 to £32,400, plus employer NI at 15% above £5,000, plus a 3% minimum pension: roughly £33,000 to £37,000 a year for one person, before recruitment, training, holiday cover, software and management time. Salary figures from Indeed UK and Totaljobs; rates from gov.uk; all checked 4 September 2026. Your figure will differ by region and seniority.
The cost nobody budgets for. One credit controller is a single point of failure. When they are on holiday, off sick or hand in their notice, chasing stops, and the ledger ages at exactly the moment nobody is watching it. That gap is invisible in the salary comparison and very visible in the cash flow.
Outsourced vs in-house vs software: the comparison
There are three ways to run credit control, and a fourth that combines two of them. They differ less on price than on who holds the risk.
| In-house credit controller | Outsourced service | Credit control software | |
|---|---|---|---|
| Cost basis | Salary plus on-costs, fixed regardless of workload | Retainer, hourly, or percentage; quoted, rarely published | Subscription, usually published, by revenue or invoice volume |
| Who does the chasing | Your employee | The provider's staff, in your name | Automated, with your team handling replies |
| Visibility | High, if they keep good records | Depends entirely on the provider's reporting | High, everything is logged |
| Customer relationship | Personal, consistent | Professional, but a third party is talking to your customers | Consistent tone, less judgement on edge cases |
| Cover for absence | None unless you have two | Built in | Automation does not take holidays |
| Scales with growth | Only by hiring again | By renegotiating the fee | By moving up a plan |
| Escalation to collections | Separate agency, history lost | Often the same provider | Some platforms include it |
| Time to start | Weeks to months (recruit, onboard) | One to four weeks | Days |
The fourth option: software with a dedicated specialist
The weakness of a traditional outsourced service is visibility: you hand over the ledger and see what the provider chooses to report. The weakness of software alone is that somebody still has to handle the replies, the disputes and the phone calls. The combination addresses both, and it is how Chaser Care is built.
According to its service page, Care gives you full access to the Chaser platform, so every reminder, reply and call note is visible to you in real time, plus a named accounts receivable specialist who runs the chasing process: multi-channel reminders by email, SMS, phone and letter in your tone, first-line dispute handling, payment reconciliation, and complete setup of your schedules and templates. When an account needs more than chasing, it can go to Chaser's collections service from inside the same platform, so the history travels with it. Pricing is an add-on to any software plan, set by revenue band, and published on the pricing page rather than quoted after a call.
The trade-off is that it suits businesses that want to stay close to their receivables rather than hand them over entirely. If you want to never think about credit control again, a fully outsourced service is the closer fit. If you want someone else to do the work but to see everything they do, this is the model.
When outsourcing credit control is the right call, and when it is not
Outsource when: your ledger has grown past what the finance manager can chase alongside the day job; you have one credit controller and no cover; overdue debt is rising and you cannot recruit fast enough; or you need multi-channel chasing (phone, letter) that your team will not do consistently.
Think twice when: your customers are a small number of high-value relationships where the personal touch is the point; your invoices are mostly disputed rather than forgotten, since a third party cannot resolve a dispute about your work; or your problem is really a process problem, such as no payment terms on invoices, which outsourcing will chase but not fix. In those cases, credit control software with your own team on the replies often gets further for less.
Seven questions to ask any outsourced credit control provider
- Who exactly will chase my customers? A named person or a pool? What is their experience, and who covers them?
- What will I be able to see, and when? A monthly report, or a live view of every reminder and reply?
- Whose name and tone goes on the reminders? Yours, theirs, or a choice per customer?
- How does it connect to my accounting system? Native integration with Xero, Sage or QuickBooks, or a spreadsheet you send them?
- What happens at 60 and 90 days overdue? Is escalation to collections included, priced separately, or handed to another company?
- What is the contract term and notice period? Rolling monthly, or a twelve-month lock-in?
- How is the fee calculated, and what moves it? Get the four variables above in writing so the quotes are comparable.
FAQs
What is the average salary for a credit controller in the UK?
On 4 September 2026, Indeed UK reported an average credit controller salary of £28,513 a year, and Totaljobs reported an industry average of £32,400 with a typical range of £26,500 to £40,700. Add employer National Insurance at 15% above £5,000 and a minimum 3% pension contribution and the cost of employing one is roughly £33,000 to £37,000 a year before recruitment, training and cover.
How much does outsourced credit control cost?
Most UK providers do not publish prices; every provider ranking on page one for this search on 4 September 2026 quotes after a call. The few that do publish a starting figure put it at roughly £299 to £597 plus VAT a month for a small ledger (Credit Control Assist and CM Group, checked 4 September 2026). Fees follow one of four models: a monthly retainer, an hourly or day rate, a percentage of cash collected, or a software subscription with a named specialist added on. The quote moves on your number of accounts and invoices, the channels used, the volume of disputes, and whether collections escalation is included.
What is receivables outsourcing?
Receivables outsourcing, also called outsourced credit control or accounts receivable outsourcing, is paying a third-party provider to manage the work of getting your invoices paid: sending reminders, handling payment queries, reconciling payments and escalating overdue accounts. The invoices stay yours and the money is paid to you; the provider does the chasing.
What are the two main types of credit control methods?
In business credit control, the two types are preventive and reactive. Preventive credit control happens before an invoice is overdue: credit checks, clear payment terms, and reminders sent ahead of the due date. Reactive credit control happens after: overdue reminders, phone calls, payment plans and escalation to collections. The best results come from doing more of the first so you need less of the second. The same phrase is also used in economics for the tools a central bank uses to manage lending, which is a different subject.
Who does credit control collect for?
Credit control collects for the business that issued the invoice. Whether the credit controller is an employee, an outsourced provider or a piece of software, the money is owed to and paid to the business, and the credit control function's job is to make that happen on time while keeping the customer relationship intact.
What are the disadvantages of outsourced credit control?
The main ones are reduced visibility, since you see what the provider reports rather than everything that happens; a third party speaking to your customers, which matters more for high-value relationships; limited ability to resolve disputes about your own work; contract lock-ins; and fees that are hard to compare because most providers do not publish them. A service that gives you live access to the platform its specialist uses removes the first of those.
Do you need a qualification to be a credit controller?
No, there is no legal requirement. The Chartered Institute of Credit Management (CICM) offers Ofqual-regulated qualifications at Level 2 (entry), Level 3 (intermediate, described by CICM as the benchmark for credit controllers in senior operational roles) and Level 5 (advanced), and some employers ask for them or for evidence of working towards them. When choosing an outsourced provider, asking whether its specialists hold or are working towards CICM qualifications is a fair test of professionalism.
Get the chasing done, and see every step of it
Chaser Care gives you a named receivables specialist working inside the Chaser platform, so your invoices get chased by email, SMS, phone and letter in your tone, and you can see everything that was sent and said.
Speak to an expert See how Chaser Care worksSalary figures from Indeed UK and Totaljobs, employer National Insurance and pension rates from gov.uk, CICM qualification levels from cicm.com, and provider pricing checks against the service pages of every provider ranking on page one of Google UK for "outsourced credit control" plus creditcontrolassist.co.uk and cmgroupuk.com, all on 4 September 2026. Late payment statistics are from Chaser's 2026 accounts receivable report. Chaser Care scope is from its service page on the same date. Last reviewed 4 September 2026.